The Challenger Retirement Fund (the Fund) is a superannuation fund which services a specific need for you. The investment objective of the Fund is to provide you with a guaranteed income stream or a guaranteed rate of return so that you can plan for your retirement with certainty.
As all the products in the Fund are closed to new members, you might need to use investments outside the Fund to generate additional income in retirement. The Fund products are not intended to be the sole solution for your retirement strategy. Rather, a combination of income streams may be ideal for assisting you to achieve and balance your retirement objectives.
Horizons is our newsletter designed for retirees or those planning for their retirement. Subscribe now to receive our latest information to help you live and age well in retirement in Australia.
The Fund's Retirement Income Strategy aims to assist you to balance and achieve the three key objectives in retirement:
Income which is sustainable and stable can help you maximise your income throughout your retirement. Sustainable retirement income is income that is reliable and long-lasting. Stable retirement income is income which is constant and predictable each year. So ultimately, the aim is to have income which you can rely on and will be there for the rest of your life.
Consideration should be given in retirement to managing key risks to meeting your retirement income goals, including:
It is important to consider access to money you can draw on at any time for planned or unexpected expenses. This can help you avoid the need to withdraw from your investments at inopportune times.
A guaranteed lifetime income stream can work alongside an account-based pension
It is unlikely that a single retirement income stream alone will enable you to maximise your retirement income, manage risks and provide flexible access to your money, but a combination of income streams can help you to achieve this.
Two types of income streams which are integral to the Fund’s Retirement Income Strategy are an account-based pension and an inflation-linked lifetime income stream (guaranteed lifetime income stream). The following table compares how each type of income stream helps to address the key retirement objectives.
Account-based pension | Guaranteed lifetime income stream | |
|---|---|---|
| Regular payments | Yes | Yes |
| Longevity protection | No | Yes |
| Inflation protection | No – your payments may increase in line with inflation over time, but generally your capital isn’t protected as you are simply just withdrawing more from your balance. | Yes |
| Protection against market risk | Usually, no | Yes |
| Easy access to your money/ability to make partial withdrawals | Usually, yes | While lifetime income streams are designed to be held for life, some provide a long period where you can access a lump sum if your circumstances change. Partial withdrawals are not generally available. |
While the Fund does not have an account-based pension or lifetime income stream open for new investment, you can consider these investments outside of the Fund. You could also consider other types of income streams however they might not help you manage all your retirement objectives.
An income layering approach enables you to lock in a minimum baseline income for life while still providing access to your money. This baseline income will be available to help you meet your essential spending needs for life. Any income on top of your baseline income is considered as desired income.
An income layering strategy has three core income components:
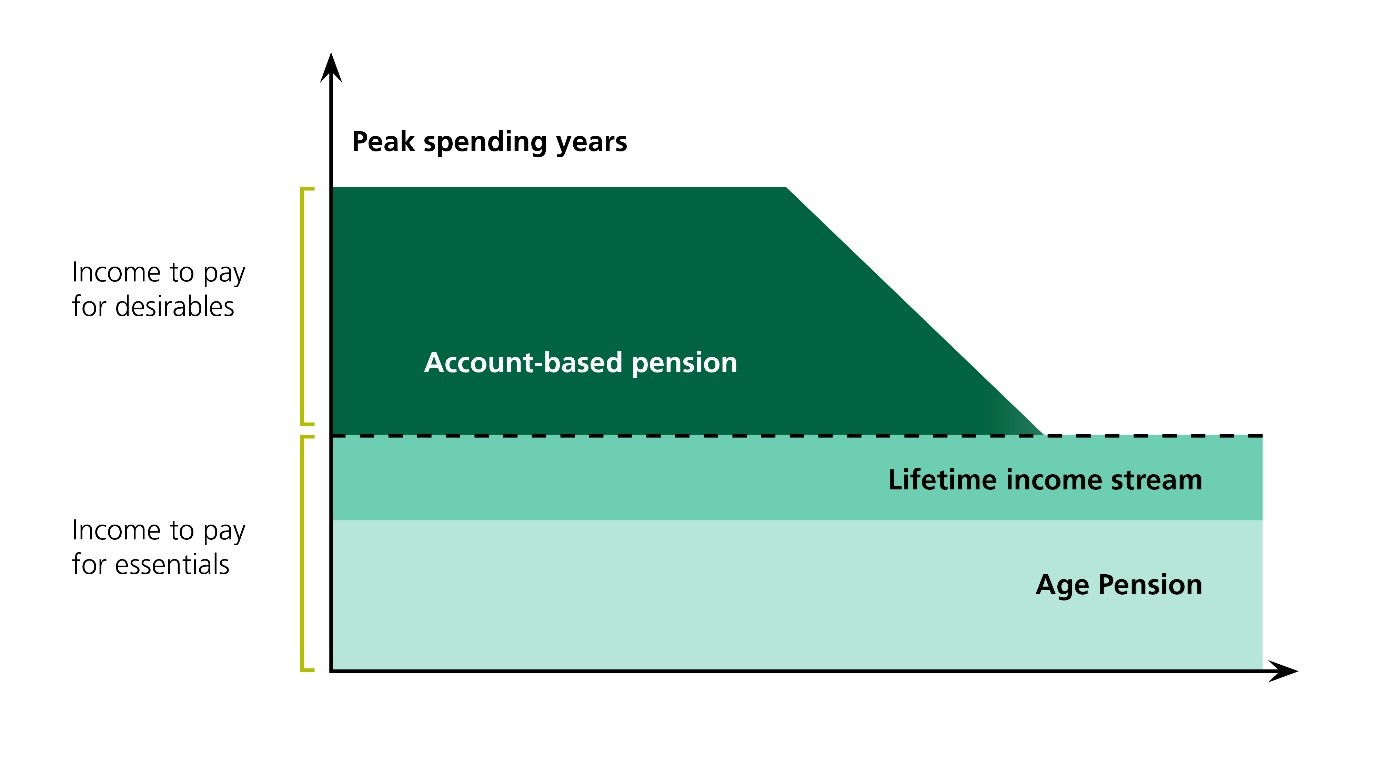
While the Age Pension is a sustainable, stable and risk-protected income stream, for many retirees it will be a safety-net only – it might not be enough to maintain your desired lifestyle in retirement and might not even cover your essential expenses. To meet your essential expenses throughout retirement, the Age Pension can work together with a secure, lifetime income stream, such as a lifetime annuity, to provide regular, top-up income payments for life. Additionally, a lifetime income stream could help boost your Age Pension today1.
Once your essential expenses have been met through a combination of the Age Pension and a lifetime income stream, you can meet your additional desired expenditure goals with income from an account-based pension. An account-based pension generally provides access to a range of investment options, allows lump-sum withdrawals and gives you the option of changing your income payments (so long as you take the required minimum each year).
An income layering strategy can therefore help you meet the three key retirement objectives:
The Age Pension and lifetime income stream help to protect against inflation, longevity and market risk, while the account-based pension provides flexible access to money. All three income streams combined can help to provide you with higher income over your retirement.
While this depends on your individual circumstances, a good starting point is to consider how much income you need in retirement.
The Association of Superannuation Funds of Australia (ASFA) publishes ‘Retirement Standard’ figures four times a year, which can help you get an idea of the income you will need to match your lifestyle income needs. The table below compares these Retirement Standards for 65-84 year old homeowners to the full Age Pension amount.
Comfortable lifestyle budget p.a. | Modest lifestyle budget p.a. | Age Pension p.a. | |
|---|---|---|---|
| Couples aged around 65 | $78,998 | $52,690 | $48,516.00 |
| Single person aged around 65 | $56,166 | $36,548 | $32,180.20 |
Full Age Pension rate as at 20 September 2026, ASFA budgets as at June 2026 quarter.
This shows that the ASFA modest retirement lifestyle is slightly above the full Age Pension amount.
If you can meet your essential expenditure needs with the full Age Pension alone then a lifetime income stream might not be necessary for you. Similarly, if you have enough money to provide your desired income for life without ever needing the Age Pension, a lifetime income stream might not be necessary for you.
However, if you are like many retirees in Australia who can’t meet their essential expenditure needs with the full Age Pension alone, and your income from other sources is not enough to meet these expenses for life, then a lifetime income stream might be necessary to maintain your lifestyle over the course of your retirement.
You should consider how much income on top of the full Age Pension amount you need to meet your essential expenses in life. Investing a proportion of your retirement savings into a lifetime income stream that will provide this amount of additional income can help you fill the gap between the full Age Pension and your essential expenditure needs.
You should consider your own personal circumstances and preferences before making any decision. Professional financial advice can help you determine how much income you need on top of the full Age Pension amount and what type of lifetime income stream is most appropriate for you.
The following useful spending planners can help you to determine whether you can live on the full Age Pension, and if not, help you determine how much lifetime income you might need on top of the full Age Pension:
It is not always easy to understand how long your retirement savings will last or how much Age Pension you will be eligible for. The Challenger Retire with Confidence tool can help you to:
Whether considering options for yourself or deciding how best to help someone close to you, it’s helpful to have access to information and tools that can help demystify planning for aged care.
Making sure your money goes the distance really matters in retirement so it’s important to understand the sources of income available to you and what role they may play in supporting you in retirement.
Estimate how long your super savings might last in retirement, possible Age Pension Payments and the impact of including a guaranteed income stream as part of your portfolio.
These spending planners for couples and singles can help you determine how much you ‘need’ (essential spending) and how much you ‘want’ (discretionary spending).
Cafe owners Fiona and Frank have recently retired. To help fund their retirement, they decided to sell their cafe and contribute the net proceeds from the sale to top-up their superannuation.
Fiona and Frank are looking for a comfortable retirement and they have estimated they will need a combined income of $73,337 p.a. (equivalent to the June 2024 ASFA ‘Comfortable’ Retirement Standard) to fund this lifestyle. They are convinced that life of the Age Pension alone is not right for them and that, as an absolute minimum, they’ll need $52,000 p.a. just to keep the lights on (or more than $7,000 more than the current maximum rate of Age Pension of $44,855 p.a. (couple combined).
View our case study on the right.
Homeowners
$350,000 each in superannuation
$20,000 in personal assets
$50,000 in cash & TDs
Getting quality financial advice can help you retire with confidence.
If you’d like some assistance finding a financial adviser, simply fill out our form online and let us know some of the things you’d like to speak with an adviser about.
We’ll contact you with a shortlist of financial advisers for you to choose from2. A financial adviser can help you tailor a retirement income solution for your situation.
The Government also has information available on their Money Smart website, including:
Guaranteed Allocated Pension is a low-risk account-based pension which offers a guaranteed fixed rate investment option and a cash investment option.
If you have a Guaranteed Allocated Pension product you are protected from market and sequencing risk, as your investments are not impacted by market volatility. The returns are competitive for low-risk investments and have no fees, which helps you to maximise your retirement income. However, the Guaranteed Allocated Pension is not designed to help you to manage inflation or longevity risk.
If you are invested in the cash investment option, you have flexible access to your savings – you can easily withdraw a lump sum (in part or in full) at any time.
If you are invested in the fixed rate investment option, your fixed rate investments are designed to be held until the end of the investment term, when you can access your savings. However, you can choose to break your fixed term (break costs apply) and access your savings before the end of the term if your circumstances change.
As part of an income layering strategy, the income you receive from your Guaranteed Allocated Pension is recommended for your desirable, non-essential needs. It might not be suitable as a source of income to meet your essential needs as it might not last your whole life, and the value of your income can deteriorate over time as a result of inflation.
To ensure you have enough income to meet all of your essential expenditure requirements for your lifetime, you should consider investing a portion of your retirement savings in an inflation-linked, lifetime income stream. A lifetime income stream can help you cover longevity, inflation and market risks. Additionally, a lifetime income stream could help you boost your Age Pension today1, which might help you with maximising your retirement income. However, as a lifetime income stream is intended to be held for life, it does not have flexible access to money.
You can’t add more money into your existing income stream. If you need flexible access to additional funds to meet your desired, non-essential expenses in the future, you should consider investing any additional superannuation amounts in an account-based pension outside the Fund.
Because all the Fund’s products are closed, including the Guaranteed Allocated Pension product, you can’t commence a new income stream or invest new money in an account-based pension with the Fund.
Guaranteed Personal Superannuation is a superannuation fund which offers a guaranteed fixed rate investment option and a cash investment option.
If you have a Guaranteed Personal Superannuation product you are protected from market and sequencing risk, as your investments are not impacted by market volatility. However, the Guaranteed Personal Superannuation is not designed to help you to manage inflation or longevity risk and you cannot draw an income from this product.
If you are invested in the cash investment option, you have flexible access to your savings – you can easily withdraw a lump sum (in part or in full) at any time once you’ve met a condition of release.
If you are invested in the fixed rate investment option, your fixed rate investments are designed to be held until the end of the investment term, when you can access your savings. However, you can choose to break your fixed term (break costs apply) and access your savings before the end of the term if your circumstances change.
If you are in or approaching retirement, you can consider investing your retirement savings in a layered solution, as described in this Retirement Income Strategy, in line with your personal circumstances and implemented with products from outside the Fund.
If you are not in or approaching retirement, the key retirement objectives might not be a consideration for you yet. At the appropriate time, you can consider a layered solution, as described in this Retirement Income Strategy, in line with your personal circumstances and implemented with products from outside the Fund.
Because the Fund’s products are closed, you can’t commence a new income stream with the Fund.
Term Life is a ‘risk-only’ insurance offering within super that offers Death cover to members, which includes terminal illness and Total and Permanent Disability (TPD) cover (issued by MetLife Insurance Limited).
If you have a Term Life product, the product does not enable you to achieve any of the key retirement objectives. You do not receive income from this product, you can’t access money, and the product does not address any of the key retirement risks. The product is designed to address insurance needs for you during your working life, not retirement.
If you have other sources of retirement savings to invest, you can consider investing your retirement savings in a layered solution, as described in this Retirement Income Strategy, in line with your personal circumstances and implemented with products from outside of the Fund.
Because the Fund is closed, you can't apply to for an increase to your sum insured amount, apart from annual Consumer Price Indexation increases.
Guaranteed Lifetime Pension Plan offers either a lifetime pension which pays guaranteed income for life or a term pension which pays guaranteed income for a set number of years.
If your Guaranteed Lifetime Pension Plan has a withdrawal value, which includes all term pensions and some lifetime pensions, then you are covered by the Fund’s Retirement Income Strategy. If you have a lifetime pension which does not have a withdrawal value, you are not covered by the Fund’s Retirement Income Strategy, given the non-commutable nature of your product.
Your Guaranteed Lifetime Pension Plan protects you from market and sequencing risk as your investments are not impacted by market volatility (except for lifetime pension members with market-linked indexed payments). However, it is not designed to provide you flexible access to your savings – you can choose to break your income stream and withdraw a lump sum however break costs apply.
You may be protected against inflation risk depending on your payment indexation option:
If you have an income stream with Partial CPI, Fixed, Market-linked or No indexation, you should consider a CPI-linked lifetime income stream to fully protect your retirement income from inflation risk.
If you have a lifetime pension as part of the Guaranteed Lifetime Pension Plan you are protected from longevity risk, as you will receive payments for your lifetime regardless of how long you live. As part of an income layering strategy, the income you receive from your lifetime pension is recommended for your essential needs. To ensure you have enough income to meet all of your desirable, non-essential needs, you should consider investing a portion of your retirement savings in an account-based pension. An account-based pension can help you meet your desirable expenses and have flexible access to your savings, however they generally do not cover longevity, inflation and market risks. If you have a deferred lifetime pension, you should consider planning to have enough capital and/or income until your payments commence at the end of the deferral period.
If you have a term pension as part of the Guaranteed Lifetime Pension Plan you are not protected from longevity risk, as your payments are not guaranteed to last for your lifetime. As part of an income layering strategy, the income you receive from your term pension is recommended for your desirable, non-essential needs as it might not last your whole life. To ensure you have enough income to meet all of your essential expenditure requirements for your lifetime, you should consider investing a portion of your retirement savings in an inflation-linked, lifetime income stream. A lifetime income stream can help you cover longevity, inflation and market risks. Additionally, a lifetime income stream could help you boost your Age Pension today1, which might help you with maximising your retirement income. However, as a lifetime income stream is intended to be held for life, it does not have flexible access to money.
You can’t add more money into your existing income stream. If you need to meet key retirement objectives that your product does not cater for, you should consider investing any additional superannuation amounts in an income stream product outside the Fund.
Because all the Fund’s products are closed, including the Guaranteed Lifetime Pension Plan product, you can’t commence a new income stream with the Fund.
Guaranteed Income Pension Plan offers either a lifetime pension which pays guaranteed income for life or a term pension which pays guaranteed income for a set number of years.
If you have a term pension you are covered by the Fund’s Retirement Income Strategy. If you have a lifetime pension, your product does not have a withdrawal value and you are not covered by the Fund’s Retirement Income Strategy, given the non-commutable nature of your product.
Your Guaranteed Income Pension Plan protects you from market and sequencing risk as your investments are not impacted by market volatility. However, it is not designed to provide you flexible access to your savings – you can choose to break your income stream and withdraw a lump sum however break costs apply.
You may be protected against inflation risk depending on your payment indexation option:
No indexation – you are not protected against inflation and the value of your income can deteriorate over time.
If you have a term pension as part of the Guaranteed Income Pension Plan you are not protected from longevity risk, as your payments are not guaranteed to last for your lifetime. As part of an income layering strategy, the income you receive from your term pension is recommended for your desirable, non-essential needs as it might not last your whole life. To ensure you have enough income to meet all of your essential expenditure requirements for your lifetime, you should consider investing a portion of your retirement savings in an inflation-linked, lifetime income stream. A lifetime income stream can help you cover longevity, inflation and market risks. Additionally, a lifetime income stream could help you boost your Age Pension today1, which might help you with maximising your retirement income. However, as a lifetime income stream is intended to be held for life, it does not have flexible access to money.
You can’t add more money into your existing income stream. If you need to meet key retirement objectives that your product does not cater for, you should consider investing any additional superannuation amounts in an income stream product outside the Fund.
Because all the Fund’s products are closed, including the Guaranteed Income Pension Plan product, you can’t commence a new income stream with the Fund.
Term Allocated Pension is a low-risk term allocated pension which offers a guaranteed fixed rate investment option and a cash investment option for a set number of years.
If you have a Term Allocated Pension product you are protected from market and sequencing risk, as your investments are not impacted by market volatility. The returns are competitive for low-risk investments and have no fees, which helps you to maximise your retirement income. However, the Term Allocated Pension is not designed to help you to manage inflation or longevity risk.
If you are invested in the cash investment option, you have flexible access to your savings – you can easily withdraw a lump sum (in part or in full) at any time.
If you are invested in the fixed rate investment option, your fixed rate investments are designed to be held until the end of the investment term, when you can access your savings. However, you can choose to break your fixed term (break costs apply) and access your savings before the end of the term if your circumstances change.
As part of an income layering strategy, the income you receive from your Term Allocated Pension is recommended for your desirable, non-essential needs. It might not be suitable as a source of income to meet your essential needs as it might not last your whole life, and the value of your income can deteriorate over time as a result of inflation.
To ensure you have enough income to meet all of your essential expenditure requirements for your lifetime, you should consider investing a portion of your retirement savings in an inflation-linked, lifetime income stream. A lifetime income stream can help you cover longevity, inflation and market risks. Additionally, a lifetime income stream could help you boost your Age Pension today1, which might help you with maximising your retirement income. However, as a lifetime income stream is intended to be held for life, it does not have flexible access to money.
You can’t add more money into your existing income stream. If you need flexible access to additional funds to meet your desired, non-essential expenses in the future, you should consider investing any additional superannuation amounts in an account-based pension outside the Fund.
Because all the Fund’s products are closed, including the Term Allocated Pension product, you can’t commence a new income stream with the Fund.
The Retirement Income Strategy is designed for members who are in or approaching retirement, which we have defined as 60 years or older.
If you have a lifetime pension within the Guaranteed Lifetime Pension Plan or Guaranteed Income Pension Plan which does not have a withdrawal value, you are not covered by this strategy, given the non-commutable nature of your product. You may still benefit from the educational materials provided as part of the above Retirement Income Strategy.
If you have any other product, please see the ‘How your product fits into the Strategy’ section above.
The period of retirement is intended to cover the period from the start of your retirement for however long you live.
The average age which we expect members to live until is based on the Australian Life Tables (ALT) produced by the Australian Government Actuary (AGA). The mortality rates used are the ALT 2015-17 tables with 25-year improvement factors, allowing for the fact that people are living longer due to improvements in medicine, science and nutrition.
It is important for you to consider that approximately half of all retirees will live past their life expectancy, meaning it may be a significantly longer time that you need income for.
Average life expectancy | From birth | From Age Pension age 67 | From age 67 with mortality improvements |
|---|---|---|---|
| Males | 81 | 85 | 88 |
| Females | 85 | 88 | 90 |
This will be different for most retirees.
The Association of Superannuation Funds of Australia (ASFA) updates the ‘Retirement Standard’ figures four times a year, which can help you get an idea of the income you will need to match your lifestyle income needs.
Association of Superannuation Funds of Australia (ASFA) Retirement Standard figures
Comfortable lifestyle budget p.a. | Modest lifestyle budget p.a. | |
|---|---|---|
| Couples aged around 65 | $78,998 | $52,690 |
| Single person aged around 65 | $56,166 | $36,548 |
The following useful spending planners are based on the ASFA retirement standard figures and can help you to determine whether you can live on the full Age Pension, and if not, help you determine how much lifetime income you might need on top of the full Age Pension:
If you can meet your essential expenditure needs with the full Age Pension alone then a lifetime income stream might not be necessary for you. Similarly, if you have enough money to provide your desired income for life without ever needing the Age Pension, a lifetime income stream might not be necessary for you.
However, if you are like many retirees in Australia who can’t meet their essential expenditure needs with the Age Pension alone, and your income from other sources is not enough to meet these expenses for life, then a lifetime income stream might be helpful to maintain your lifestyle over the course of your retirement.
You should consider how much income on top of the full Age Pension amount you need to meet your essential expenses in life. Investing a proportion of your retirement savings into a lifetime income stream that will provide this amount of additional income can help you fill the gap between the full Age Pension and your essential expenditure needs.
You should consider your own personal circumstances and preferences before making any decision. Professional financial advice can help you determine how much income you need on top of the full Age Pension and what lifetime income stream product is most appropriate for you.